


By Candour Legal Team · Legal position reviewed on 15 November 2026
A manufacturer issuing shares on an SME exchange needs two arrangements. Before subscriptions open, underwriters commit to cover the entire offer, including an own-account commitment by the lead manager or managers of at least 15% of the issue size. After listing, an issuer-appointed broker makes a market in the shares for at least three years. The first arrangement answers who will subscribe if the issue falls short. The second gives investors a bid and an offer against which they may trade. ICDR regulations 260–261.
Follow the ₹20 crore IPO example
Before opening: record who backs the offer
Under regulation 260 of SEBI’s Issue of Capital and Disclosure Requirements Regulations, 2018, the issuer consults the lead managers and appoints SEBI-registered merchant bankers or stockbrokers as underwriters. The lead managers may also agree with nominated investors on the number of securities those investors will subscribe for at the issue price if the offer is undersubscribed. Coverage must extend to 100% of the offer even where a lower amount would meet a minimum-subscription test. ICDR regulation 260(1)–(3).
One day before the issue opens, the lead managers must file an undertaking with SEBI confirming full underwriting. It must list the underwriters, nominated investors and sub-underwriters and the extent of each commitment. The offer document must disclose the arrangements. If another underwriter fails to meet its obligation or a nominated investor fails to subscribe to the unsubscribed portion, the lead managers must fulfil the underwriting obligations. ICDR regulation 260(4)–(7).
Worked example: ₹20 crore of coverage and a ₹1.5 crore shortfall
Assume one lead manager and an all-fresh SME IPO of 20 lakh shares at ₹100 each. The issue is ₹20 crore. The lead manager’s minimum own-account commitment is ₹3 crore, equivalent to 3 lakh shares. That amount is included in the ₹20 crore of underwriting. The board should be able to reconcile the amounts allocated to all parties to the total and identify who covers each uncovered subscription.
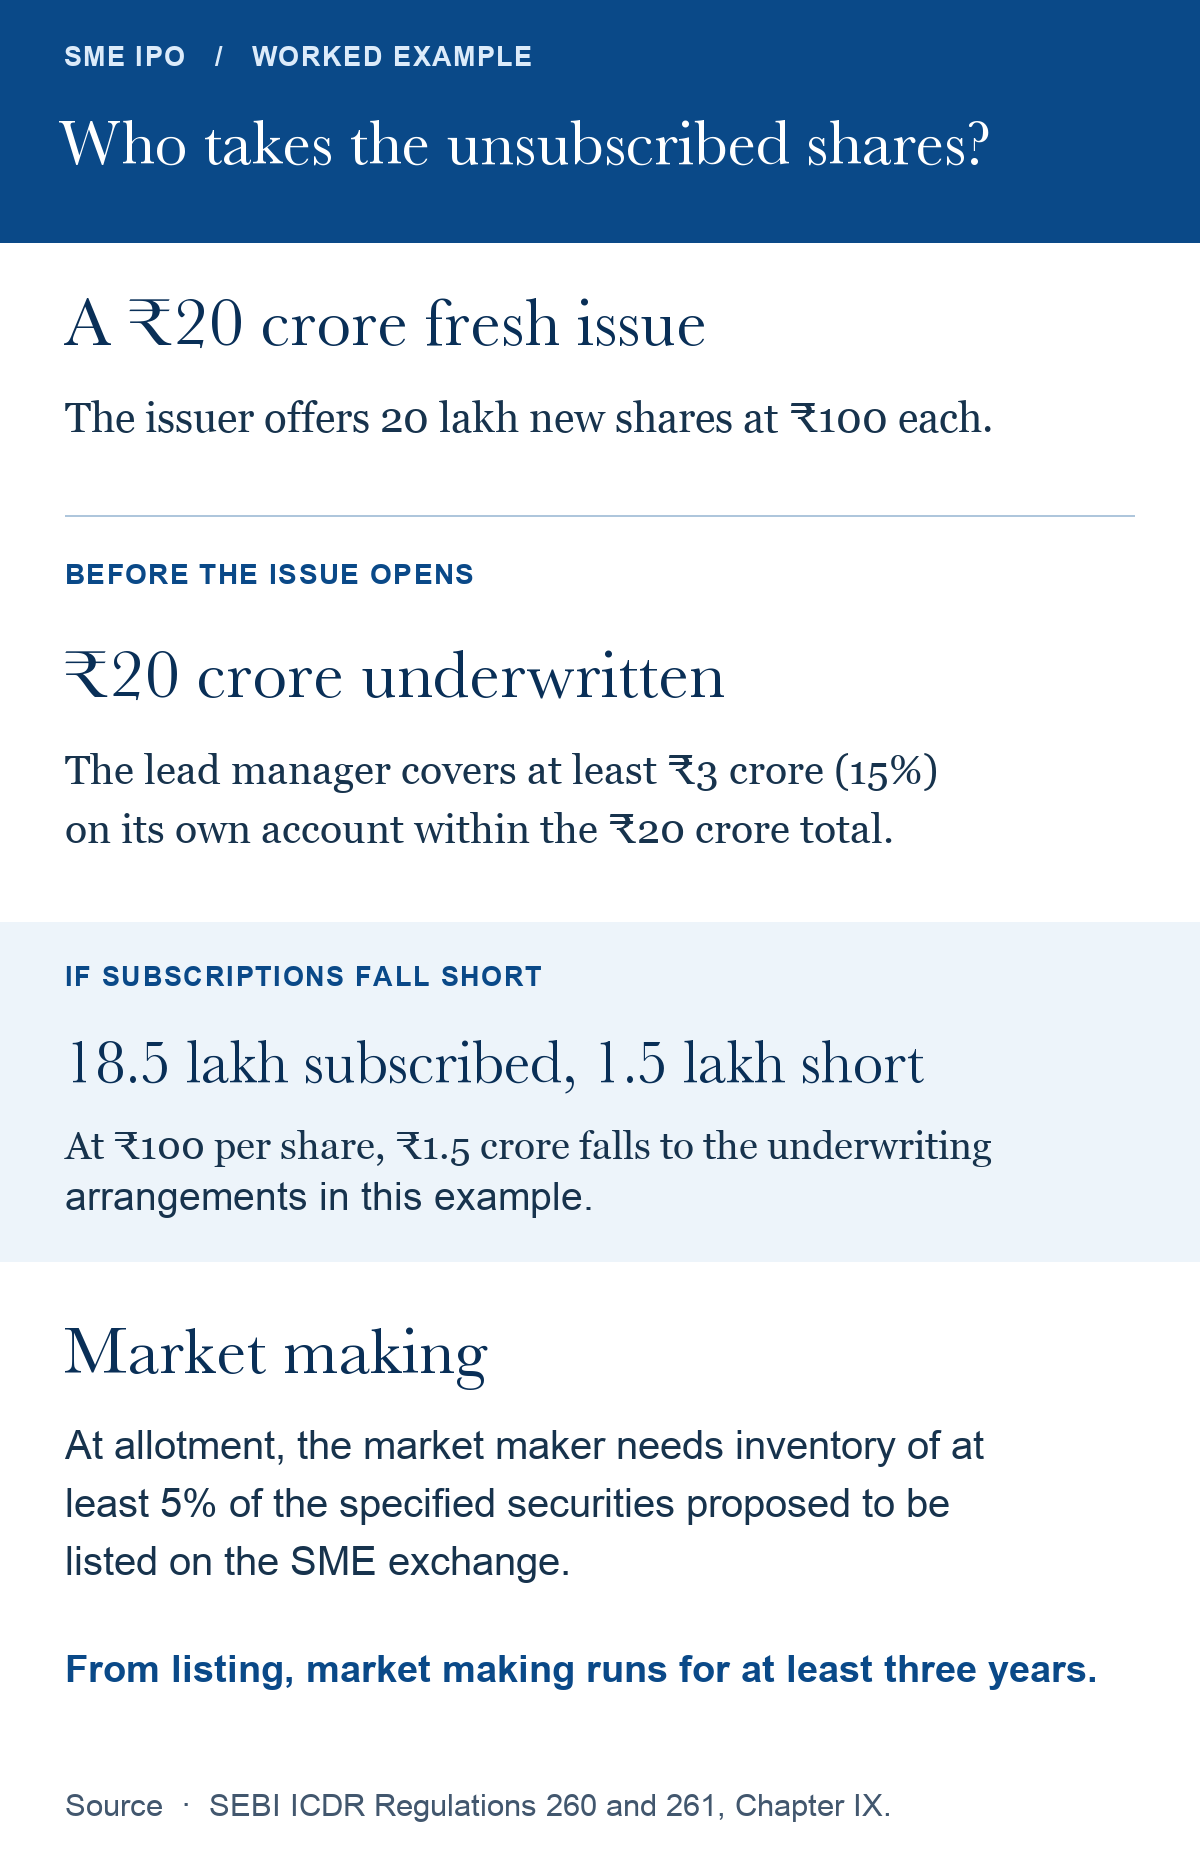
Now suppose valid subscriptions, including any applicable fixed allocations, cover 18.5 lakh shares. Assume the remaining 1.5 lakh shares are the only shortfall. At ₹100 each, this is ₹1.5 crore. The parties must apply the underwriting agreements to determine who subscribes to that balance. The ₹3 crore commitment does not mean the lead manager automatically buys 3 lakh shares. The issue team must still check the other applicable allotment and listing conditions.
At allotment and listing: arrange the market maker’s inventory and quotes
The lead managers must ensure compulsory market making through a broker of the SME exchange appointed by the issuer. For an IPO, the minimum three-year period starts on listing. A separate starting point applies on migration from the main board under regulation 276. The issuer must describe its market-making arrangement in the offer document. Any arrangement with nominated investors to deliver or receive securities for market making requires the SME exchange’s prior approval. ICDR regulation 261(1)–(3).
Inventory is tested earlier. At allotment the market maker must hold at least 5% of the specified securities proposed to be listed on the SME exchange. That requirement has its own measurement date and base. The trading obligation then works through the order book. For continuous trading on NSE Emerge, NSE describes two-way quotes at least one trading lot deep for at least 75% of the session time. The exchange applies its spread and session rules. If the maker exhausts its inventory through exchange trades, NSE prescribes notification with supporting evidence and buy-only quoting until stock is reacquired. NSE surveillance circular, market-maker obligations. ICDR regulation 261(4) · NSE Emerge trading system · NSE market-maker requirements.
Consider a shareholder seeking to sell three lots. A displayed bid for one lot shows the price and quantity available at that point. A larger sale depends on the remaining bids, their quantities and intervening trades. The market maker’s presence can help a buyer and seller find a price. It does not set a floor at the IPO price or promise an immediate exit for the full order.
Checks for the issuer, lead manager and investors
- Before the offer. Verify the intermediaries’ registration and signed commitments. NSE also requires the book-running lead manager and issuer to check a proposed market maker’s financial capacity at appointment. NSE market-maker eligibility circular. Record who assesses a shortfall, makes a call under each agreement and funds the balance if a counterparty defaults.
- Before allotment. Check the inventory evidence, proposed listing date, exchange approvals and arrangements to maintain the required service if the appointed broker changes. Preserve distinct records for the underwriting and market-making roles.
- When reading the prospectus. Compare the underwriting and market-making disclosures. Check the identity of each counterparty, the size and nature of its obligation and any fees disclosed. A market maker cannot purchase from promoters, promoter-group members or their transferees during the compulsory period in the circumstances covered by regulation 261(6). ICDR regulation 261(6)–(7).
Find the draft offer document and check its disclosures
SEBI’s October 2026 consultation proposes replacing the mandatory 100% underwriting and 15% own-account requirements with a main-board-style framework. It also proposes removing compulsory market making. These are proposals as of 15 November 2026. An issuer preparing an SME IPO must continue to apply regulations 260 and 261. SEBI consultation, §5.6.1 · SEBI consultation, §5.6.2.
Frequently asked questions
If the SME issue is fully subscribed, must the lead manager still buy 15%?
The 15% requirement is an own-account underwriting commitment. It does not create an automatic allotment or purchase of 15% solely because the lead manager signed the undertaking. Any subscription must be considered under the applicable arrangements.
Who is responsible if an appointed underwriter fails to perform?
Regulation 260(5) places the underwriting obligation on the lead manager or managers if another underwriter defaults or a nominated investor fails to subscribe to the unsubscribed portion.
Does a five per cent inventory mean five per cent must be available for sale every day?
Regulation 261(4) measures the market maker’s minimum inventory at allotment against the specified securities proposed to be listed. The quantity quoted for a trade after listing depends on the applicable exchange rules and order book.
Can an investor sell the whole holding back to the market maker at the IPO price?
Market making does not promise a sale at the IPO price. Regulation 261(5) contains a specific rule for buying a holder’s entire holding in one lot where its value is below the exchange’s minimum contract size. That rule sets no guaranteed resale price.
Speak to a senior advocate about your matter.
Tell us what's going on. We review every enquiry personally and reply within 24 working hours.
Schedule a Consultation
Takes under a minute. We'll come back to you within 24 working hours.
Request received.
Thank you — a Candour Legal advocate will contact you within 24 working hours.
Urgent? Call us right away.
Disclaimer — Bar Council of India
As per the rules of the Bar Council of India, advocates and law firms are not permitted to solicit work or advertise. This website is intended solely to provide general information about Candour Legal and its areas of practice, and is made available to the user only at the user's own specific request. The contents of this website do not constitute, and should not be construed as, legal advice, an advertisement, a solicitation or an invitation of any kind. Candour Legal assumes no liability for any action taken in reliance on the material on this website; readers facing a legal issue should seek appropriate professional advice on their specific circumstances. Use of this website, or transmission of any enquiry through it, does not create a lawyer-client relationship between the user and Candour Legal.
BEFORE YOU GO
Get a free 15-minute case assessment
Tell us what's going on and a Candour Legal advocate will call you back — no charge, no obligation.
Schedule my free assessment Call now