Candour Legal – Best Lawyers in Ahmedabad | Law firm in Ahmedabad


For decades, a foreign investor wanting to trade Indian equity derivatives ran the same route: set up an entity in Mauritius, obtain a Tax Residency Certificate, sign the India-Mauritius Double Taxation Avoidance Agreement, and let treaty protection handle the rest. That architecture is unwinding. The India-Mauritius DTAA was substantially amended in 2016, tightening source-based taxation of capital gains and stripping the treaty of much of its utility for short-term trading strategies. GIFT City — specifically the Category III Alternative Investment Fund route under the IFSCA (Fund Management) Regulations, 2025 — is now the most tax-efficient legal pathway for a foreign investor to access Indian Futures and Options on the NSE IFSC and India INX, within India’s legal perimeter, without treaty dependency. Whether GIFT City is unambiguously the better structure depends on a layer of GAAR analysis that much of the current commentary summarises but does not fully resolve.
Key Takeaways
- A Category III AIF registered with IFSCA in GIFT City can trade Indian Futures and Options on NSE IFSC and India INX with no Securities Transaction Tax, and its income from trading specified securities is exempt under the specified-fund exemption, which is not limited to a ten-year holiday (the separate IFSC unit deduction is 100% for any ten consecutive years out of fifteen).
- The statutory tax exemption under Schedule IV of the Income-tax Act, 2025 does not by itself exclude GAAR under Chapter XI (Sections 178–184) — GAAR applies to any impermissible avoidance arrangement (main purpose of obtaining a tax benefit plus any tainted element), subject to the exclusions in the GAAR rules (such as the Rs 3 crore threshold and FPIs not claiming treaty benefit).
- IFSCA requires genuine substance at the GIFT City level: a Fund Management Entity with registered presence, at least two Key Management Personnel, and investment decisions taken within the IFSC.
- Cumulative AIF commitments in GIFT City exceeded USD 12 billion by March 2026. Category III is the fastest-growing category, primarily on the strength of F&O and derivatives strategies.
- In AAR v. Tiger Global International II Holdings, 2026 INSC 60 (15 January 2026), the Supreme Court applied statutory GAAR (Chapter X-A of the 1961 Act, Section 90(2A) and Rule 10U) to deny Mauritius treaty relief; the CBDT then amended Rule 10U with effect from 31 March 2026 to restore protection for transfers of pre-1 April 2017 investments. Funds with nominal IFSC presence and de facto portfolio management running from Singapore or Mumbai carry this risk.
- Under the India-Mauritius DTAA, a Mauritius resident’s gains from derivatives fall under the residuary Article 13(4) and are taxable only in Mauritius (the 2016 Protocol’s source-taxation rule in Article 13(3A)/(3B) covers only shares), subject to TRC, beneficial ownership and GAAR; business income is taxable in India only if attributable to an Indian PE (Article 7). GIFT City removes the treaty dependency entirely.
- The FPI route through GIFT City (distinct from the AIF route) is available for operations below the AIF minimum corpus of USD 3 million.
What the Category III AIF Route Actually Looks Like
A foreign investor wishing to trade Indian equity derivatives through GIFT City goes through three registration layers. First, a Fund Management Entity is incorporated in the IFSC and registered with IFSCA as a Category III FME under the IFSCA (Fund Management) Regulations, 2025. Second, the AIF is constituted — either as a trust or an LLP — and registered with IFSCA. Third, the AIF obtains registration on NSE IFSC or India INX as an eligible participant for the relevant derivative contracts. The minimum corpus for a Category III AIF (restricted scheme) in GIFT City is USD 3 million.
The tax package is the attraction. As an IFSC unit, the FME can claim a 100% deduction for any ten consecutive years out of fifteen, at its option. The AIF’s income from trading specified securities (which includes equity derivatives on IFSC exchanges) is exempt under the separate specified-fund exemption, which is not limited to a ten-year holiday. No STT applies to trades on NSE IFSC or India INX. GST is exempt on services provided by the FME to the AIF within the IFSC. Key Management Personnel must be resident or based in the IFSC, and investment decisions must be taken within the IFSC — a requirement that generates the most compliance friction in practice, as fund managers often prefer to retain portfolio management onshore or in Singapore while formally booking decisions in GIFT City.
| Feature | Mauritius Route | GIFT City Category III AIF |
|---|---|---|
| Tax basis | Treaty-derived (DTAA) | Statutory (Schedule IV, IT Act 2025) |
| Derivatives income | Taxable only in Mauritius under residuary Art. 13(4) (Art. 13(3A)/(3B) covers only shares), subject to TRC, beneficial ownership and GAAR; business income taxable in India only if attributable to an Indian PE (Art. 7) | Exempt under the specified-fund exemption (not limited to a 10-year holiday) |
| GAAR risk | Chapter XI, IT Act 2025 (formerly Chapter X-A, 1961 Act); statutory GAAR applied in Tiger Global | Chapter XI (Sections 178–184) not excluded merely because the exemption is statutory; judicial GAAR risk if substance thin |
| STT on trades | Applies (domestic exchange trades) | Zero (NSE IFSC / India INX) |
| Regulatory system | Mauritius FSC + Indian tax | IFSCA only — single regulator within India |
| Substance requirement | TRC + FSC substance + board meetings in Mauritius | FME + KMP + investment decisions in IFSC |
The GAAR Question
Chapter XI (Sections 178–184) of the Income-tax Act, 2025 — the statutory GAAR framework — applies to an arrangement that is an impermissible avoidance arrangement: one that lacks commercial substance and is entered into primarily for a tax benefit. Statutory GAAR is not excluded merely because the tax benefit is a statutory exemption; the exclusions are those in the GAAR rules (such as the Rs 3 crore threshold and FPIs not claiming treaty benefit). A GIFT City AIF’s tax exemption arises from Schedule IV of the Income-tax Act, 2025 — a specific, Parliament-enacted exemption. It is not treaty-derived. That alone does not take the arrangement outside statutory GAAR.
Judicial GAAR is different, but the Tiger Global ruling was not a judicial GAAR case: in AAR v. Tiger Global International II Holdings, 2026 INSC 60 (15 January 2026), the Supreme Court applied statutory GAAR (Chapter X-A of the 1961 Act, Section 90(2A) and Rule 10U) to deny Mauritius treaty relief to a Mauritius-routed investment structure; the CBDT then amended Rule 10U with effect from 31 March 2026 to restore protection for transfers of pre-1 April 2017 investments. GIFT City funds with no real decision-making presence in the IFSC — with portfolio management de facto run from Singapore or Mumbai — carry a Tiger Global-style risk. The substance requirement in the IFSCA regulations is not merely a filing requirement; it is the fund’s best defence against a judicial substance challenge.
What GIFT City Offers That Mauritius No Longer Does
The 2016 amendment to the India-Mauritius DTAA introduced a grandfathering cutoff and brought capital gains on Indian shares acquired after 1 April 2017 within India’s source-based taxation. For a derivatives-focused strategy, a Mauritius resident’s gains from derivatives fall under the residuary Article 13(4) and are taxable only in Mauritius (the 2016 Protocol’s source-taxation rule in Article 13(3A)/(3B) covers only shares), subject to TRC, beneficial ownership and GAAR; business income is taxable in India only if attributable to an Indian PE (Article 7). GIFT City removes the dependency on a treaty whose utility has narrowed, without requiring the fund to leave India’s legal and regulatory perimeter.
More practically: a Mauritius structure requires a TRC, minimum substance in Mauritius — staff, office, board meetings on the island — ongoing compliance with the Mauritius Financial Services Commission, FATCA/CRS reporting from a Mauritius-regulated entity, and ongoing management of the commercial substance test. A GIFT City FME operates under IFSCA’s supervision, with a compliance framework that Indian counsel and Indian auditors can manage without cross-border cost. Mauritius retains relevance for multi-asset, multi-jurisdiction strategies where the DTAA still protects specific categories of pre-2017 shareholdings, and a Mauritius resident’s derivative gains remain taxable only in Mauritius under the residuary Article 13(4), subject to TRC, beneficial ownership and GAAR.
The FPI Alternative
A non-resident investor whose trading operation falls below the AIF minimum corpus, or who does not want the FME overhead, can obtain Foreign Portfolio Investor registration, which is granted by a designated depository participant on behalf of SEBI rather than by NSE IFSC. The FPI route under SEBI’s FPI Regulations allows GIFT City registration with lighter infrastructure requirements than an AIF-FME structure. The tax treatment is broadly similar for derivatives. The FPI route does not provide the leverage and strategy flexibility of a Category III AIF, but for a modest derivatives operation, it is a simpler path to the same exchange access.
The Ahmedabad Proximity Advantage
GIFT City sits on the Ahmedabad-Gandhinagar border. The IFSCA’s physical presence, the NSE IFSC and India INX exchanges, the licensed banking units, and the insurance entities are all within a 15-minute drive of Ahmedabad. Legal counsel advising on GIFT City fund structuring, IFSCA registration, or FME incorporation does not need to be Mumbai-based to serve this market. For fund managers considering the GIFT City route, proximity to local counsel with IFSCA regulatory knowledge reduces both cost and turnaround time on structuring questions.
Looking Ahead
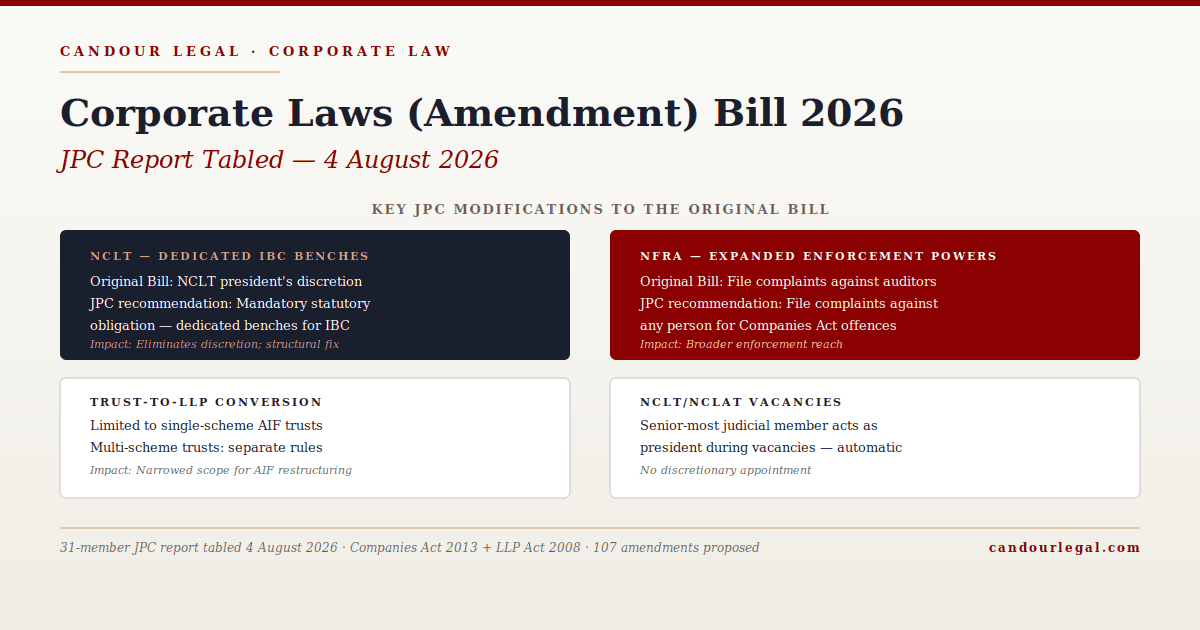
Three developments will affect the Category III AIF framework over the next twelve months. IFSCA’s implementation of the IFSCA (Fund Management) Regulations, 2025 (notified 19 February 2025, replacing the 2022 Regulations) may tighten substance requirements further, specifically addressing what counts as investment decision-making within the IFSC. SEBI is evaluating whether to allow Category III AIFs in GIFT City to trade commodity derivatives in addition to equity F&O, which would expand the addressable market for IFSC-domiciled hedge strategies. And the JPC’s recommendation on trust-to-LLP conversion for single-scheme AIFs in the Corporate Laws (Amendment) Bill, 2026 will affect fund managers currently in trust format who want to restructure. For the analysis of that Bill, see Corporate Laws (Amendment) Bill 2026: JPC Report and Key Changes for Practitioners.
Frequently Asked Questions
Can a foreign investor trade Indian Nifty futures through GIFT City?
Yes. A non-resident investor can access Indian equity index futures and options on NSE IFSC and India INX through either a Category III AIF or an FPI registration in GIFT City IFSC. Income from these trades is exempt from Indian tax under the specified-fund exemption, which is not limited to a ten-year IFSC tax holiday. No STT applies to trades on IFSC exchanges.
Does GAAR apply to a GIFT City AIF?
Statutory GAAR under Chapter XI (Sections 178–184) of the Income-tax Act, 2025 is not excluded merely because the GIFT City AIF’s tax exemption is a specific Parliament-enacted benefit under Schedule IV rather than treaty-derived; it applies to any impermissible avoidance arrangement, subject to the exclusions in the GAAR rules. GAAR remains a risk for funds without genuine substance at the IFSC level, following the Supreme Court’s application of statutory GAAR in Tiger Global (2026 INSC 60, 15 January 2026).
What is the minimum corpus for a Category III AIF in GIFT City?
USD 3 million (for restricted schemes). The Fund Management Entity must be incorporated in the IFSC, registered with IFSCA, and maintain Key Management Personnel and investment decision-making within the IFSC.
Is GIFT City better than Mauritius for a fund that trades Indian derivatives?
For a pure India F&O or equity derivatives strategy, GIFT City is structurally better in 2026. Under the Mauritius DTAA, a Mauritius resident’s gains from derivatives fall under the residuary Article 13(4) and are taxable only in Mauritius, subject to TRC, beneficial ownership and GAAR. GIFT City’s statutory tax exemption is treaty-independent, operational costs are lower, and the compliance framework is Indian — reducing cross-border overhead.
What substance does IFSCA require for a GIFT City FME?
The FME must be incorporated in the IFSC, have at least two Key Management Personnel, maintain books and records in the IFSC, and conduct investment decision-making from within the IFSC. Outsourcing portfolio management to an entity outside the IFSC risks challenge under IFSCA’s substance tests and potentially under a judicial GAAR analysis.
What is judicial GAAR and how does it affect GIFT City structures?
Judicial GAAR refers to substance-over-form analysis applied by Indian courts independent of the statutory GAAR under Chapter XI (Sections 178–184) of the Income-tax Act, 2025 (formerly Chapter X-A of the 1961 Act). In the Tiger Global litigation (2026 INSC 60, 15 January 2026), the Supreme Court applied statutory GAAR (Chapter X-A of the 1961 Act, Section 90(2A) and Rule 10U) to deny Mauritius treaty relief. A GIFT City fund with nominal IFSC presence and de facto portfolio management running from outside India carries this risk.
Speak to Candour Legal’s Capital Markets and IFSC Team
Candour Legal advises fund managers, investors, and financial institutions on GIFT City AIF structuring, IFSCA registration, FME incorporation, GAAR analysis, FPI registration, and capital markets regulatory compliance. The firm’s Ahmedabad office is located minutes from GIFT City IFSC.
Schedule a 30-minute strategy callAbout the author
Manasvi Thapar, Advocate at Candour Legal, advises on capital markets, IFSC regulatory matters, and commercial litigation. Schedule a call with Manasvi.
Candour Legal is a full-service Indian law firm with offices in Ahmedabad (adjacent to GIFT City), Mumbai, and New Delhi. More on our Capital Markets and IFSC practice.
Further reading
- India’s Data Centre Tax Holiday Till 2047: What the Finance Act 2026 Means for Investors and Operators
- Corporate Laws (Amendment) Bill 2026: JPC Report and Key Changes for Practitioners
- FIU-IND Registration in India: Who Needs It and Who Doesn’t
SEO / AEO targeting: Focus keyword — GIFT City Category III AIF F&O trading India. AEO queries targeted: “What is the Category III AIF route for F&O trading in GIFT City”, “Is GIFT City replacing Mauritius for fund structuring”, “Does GAAR apply to GIFT City funds”, “What is judicial GAAR and does it affect IFSC entities”, “What substance does IFSCA require for a GIFT City FME”. GEO-SEO: GIFT City lawyers Ahmedabad, IFSC fund counsel Gujarat, IFSCA registration lawyers GIFT City.
Speak to a senior advocate about your matter.
Tell us what's going on. We review every enquiry personally and reply within 24 working hours.
Schedule a Consultation
Takes under a minute. We'll come back to you within 24 working hours.
Request received.
Thank you — a Candour Legal advocate will contact you within 24 working hours.
Urgent? Call us right away.
Disclaimer — Bar Council of India
As per the rules of the Bar Council of India, advocates and law firms are not permitted to solicit work or advertise. This website is intended solely to provide general information about Candour Legal and its areas of practice, and is made available to the user only at the user's own specific request. The contents of this website do not constitute, and should not be construed as, legal advice, an advertisement, a solicitation or an invitation of any kind. Candour Legal assumes no liability for any action taken in reliance on the material on this website; readers facing a legal issue should seek appropriate professional advice on their specific circumstances. Use of this website, or transmission of any enquiry through it, does not create a lawyer-client relationship between the user and Candour Legal.
BEFORE YOU GO
Get a free 15-minute case assessment
Tell us what's going on and a Candour Legal advocate will call you back — no charge, no obligation.
Schedule my free assessment Call now