


By Candour Legal Team · Legal position reviewed on 14 November 2026
A manufacturer receives ₹2 crore in cash for a share issue. Another converts ₹2 crore of existing debt into shares. Both have raised their recorded share capital, yet only the first transaction adds a capital receipt under the NSE Emerge FCFE rules. The difference can decide whether a company has the two positive years of free cash flow to equity (FCFE) it needs for an SME IPO. NSE circular of 20 April 2026, FAQ 13.
What changed on 20 April 2026?
The National Stock Exchange of India (NSE) introduced its positive-FCFE test for draft red herring prospectuses (DRHPs) filed from 1 September 2024. Circular NSE/SME/73818 changed the calculation with immediate effect for DRHPs filed on NSE Emerge. It added qualifying cash proceeds from issuing capital. The issuer still needs positive FCFE in at least two of the three financial years preceding its application. Regulation 229(3) of the SEBI ICDR Regulations requires the issuer to meet the chosen SME exchange’s applicable conditions. NSE’s August 2024 circular · NSE’s April 2026 revision · ICDR regulation 229(3).
Reconstructing FCFE from the restated accounts
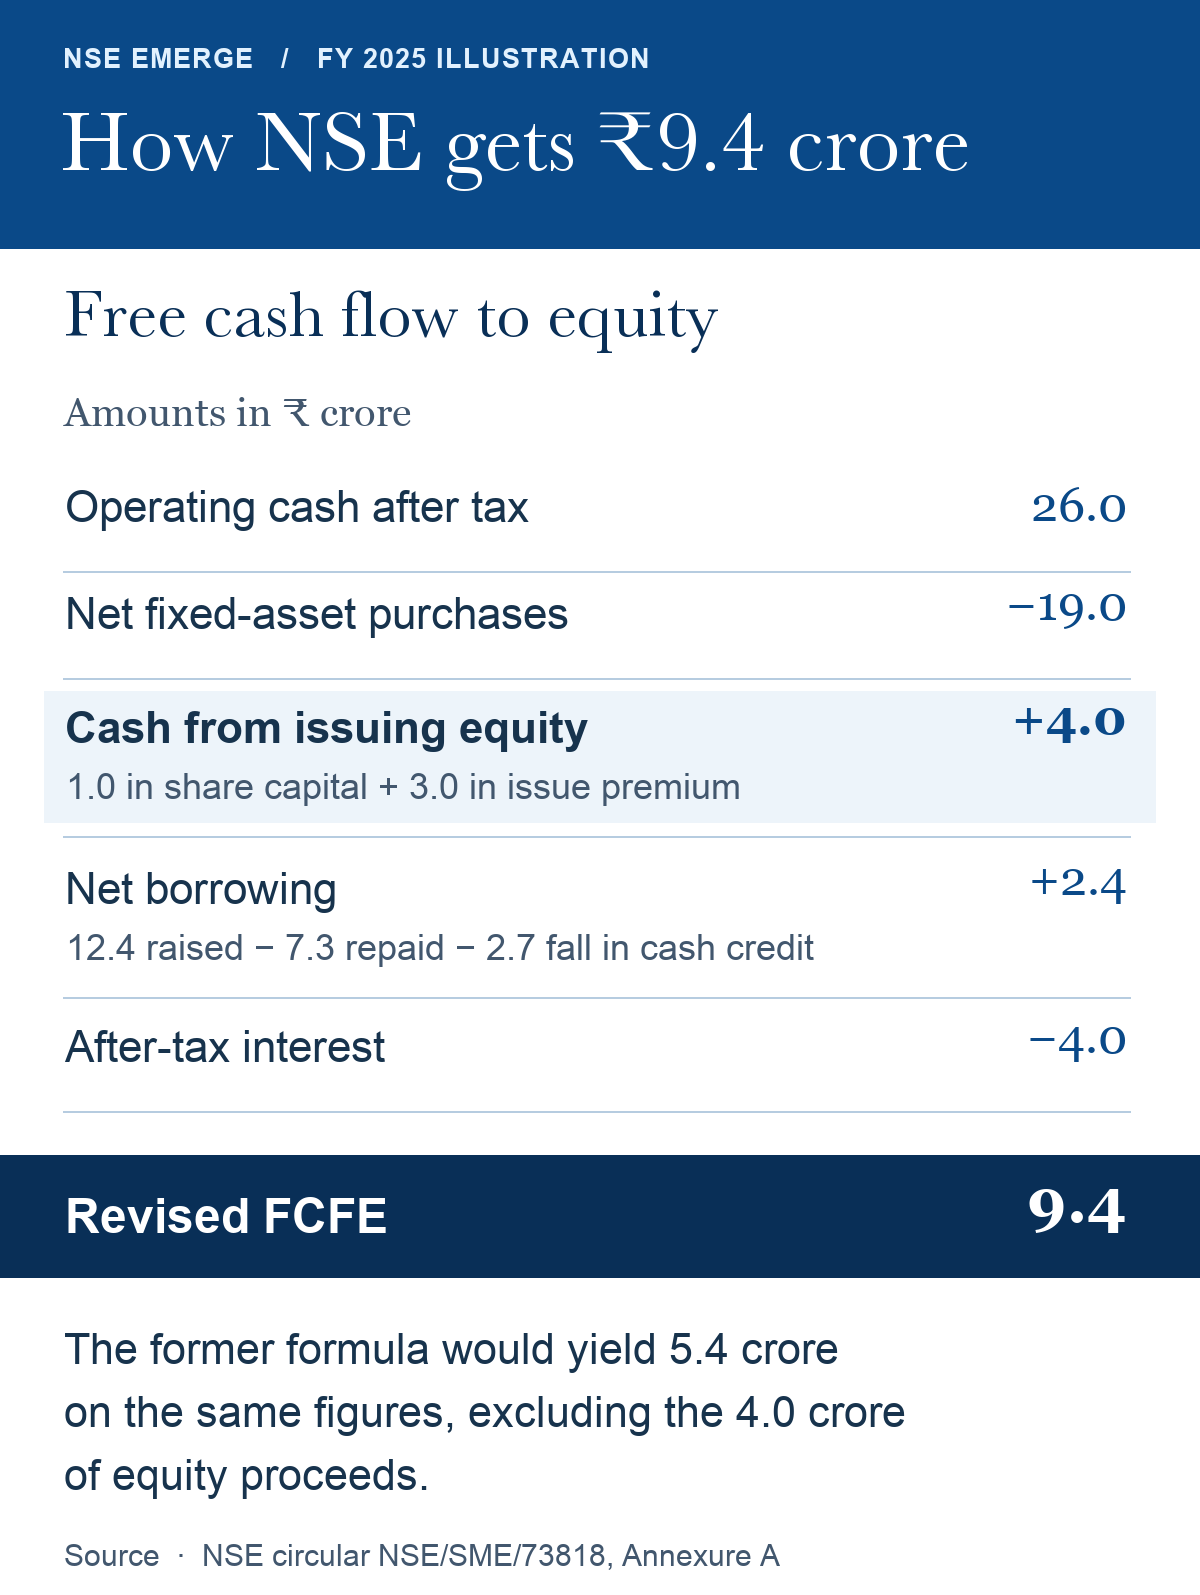
FCFE = net operating cash flow − net fixed-asset purchases + qualifying capital-issue proceeds + net borrowings − after-tax interest on borrowings. Use the restated financial statements furnished in the offer document. NSE calls for consolidated accounts where available and permits standalone accounts where consolidated accounts are unavailable or need not be furnished. Forecasts and stub periods fall outside this three-year test. NSE Annexure A and Annexure B, FAQs 1, 2 and 6.
| Input | What goes into the working |
|---|---|
| Net operating cash | Cash generated by operations after income tax paid. If the starting figure is already net of tax, use it directly. |
| Fixed assets | Purchases include plant, equipment, capital work in progress and intangible assets. Deduct applicable proceeds from sales of plant, equipment and work in progress, and add capital advances. |
| Capital receipts | Cash from issuing equity, preference capital or other instruments classified as share capital, including premium. Trace each qualifying receipt to its year. |
| Net borrowings | Long- and short-term borrowing proceeds less repayments. Count a movement in short-term borrowings only once if it already appears in operating cash flows. |
| After-tax interest | Apply the effective tax rate to interest on borrowings: multiply interest by one minus that rate. NSE derives the rate as 1 − (profit after tax ÷ profit before tax), using restated figures without a separate adjustment for exceptional items. |
Bank charges, letter-of-credit commissions and statutory late-payment penalties do not belong in borrowing interest. Convertible preference shares follow their classification in the restated accounts. Convertible debentures are treated as borrowings until conversion, with their interest included in the working in line with the accounts. For a non-banking financial company, NSE directs the issuer to include only long-term movements in net borrowings, because short-term lending and borrowing flows sit within operations, and to omit a separate deduction for interest already reflected there. NSE Annexure B, FAQs 3–11.
Two worked examples in ₹ crore
Example 1. Cash changes the result. Assume a manufacturer reports 5.0 of net operating cash, 6.0 of net fixed-asset purchases, 0.5 of net borrowing and 0.4 of after-tax borrowing interest. It also receives 2.0 for newly issued equity in the same year, made up of 0.2 face value and 1.8 securities premium. Under the revised method, 5.0 − 6.0 + 2.0 + 0.5 − 0.4 = 1.1. Omitting the cash share issue gives −0.9. If the shares had instead settled an existing debt without a cash movement, the capital-receipt input would be zero. Check that the non-cash conversion has also been excluded from cash repayments.
Example 2. Counting cash credit twice creates a false positive. A second issuer reports net operating cash of 4.0, already including a 1.2 increase in short-term cash credit. It spent 3.5 on net fixed assets, received no share capital, repaid 0.3 of long-term debt net of new drawings, and incurred 0.4 of after-tax borrowing interest. Its FCFE is 4.0 − 3.5 + 0 − 0.3 − 0.4 = −0.2. Adding the same 1.2 again under borrowings would show a misleading positive 1.0. These illustrations apply the circular’s rules to hypothetical companies. NSE Annexure B, FAQs 3 and 13.
What the merchant banker should be able to reproduce
- Three signed-off annual calculations. Retain a separate working for each year, with a reference to the relevant restated account or note for every input. A large positive year cannot offset two years that are zero or negative.
- A trail from allotment to bank receipt. Match the subscription records, bank statement, allotment resolution and cash-flow entry. Identify the cash premium separately. A ledger increase in share capital alone cannot establish that money was received.
- A reconciliation of financing and asset movements. Tie loan drawings and repayments to the cash-flow statement, strip non-cash movements from financing changes, and trace capital advances or asset disposals to their supporting schedules.
- A check at the later filing. NSE requires compliance when the draft is filed for in-principle approval and again at the red herring prospectus and prospectus stages, as applicable. If the reporting years roll forward or a restatement changes a figure, rerun the test and update the offer-document explanation. NSE FAQ 12.
FCFE is one part of admission to NSE Emerge. An issuer can pass it and still fall short on operating profit or the applicable exchange conditions. SEBI’s October 2026 consultation on SME IPO eligibility discusses a different profitability test. The draft proposals do not displace NSE’s current FCFE requirement. NSE Emerge admission criteria · NSE Emerge legal and financial readiness checklist · SEBI’s October 2026 SME IPO consultation.
Frequently asked questions
How many years of positive FCFE does NSE Emerge require?
At least two of the three financial years before application must show FCFE above zero. Calculate each year separately using the restated accounts in the offer document. A positive three-year total alone does not satisfy the test.
Can money received for shares before an IPO count?
Qualifying cash proceeds from issuing share capital in a financial year under review can count, including any securities premium. Reconcile the receipt to the cash-flow statement and the instrument’s classification. Projected IPO proceeds and non-cash allotments do not qualify.
Can a profitable stub period cure a failed year?
NSE excludes stub periods and projections from the FCFE calculation. Use the preceding three financial years and recheck the applicable years when the issuer reaches the next filing stage.
Which financial statements should a group use?
Use the restated consolidated financial statements where available. Use restated standalone accounts where consolidated accounts are unavailable or need not be furnished. Keep the same reporting basis across the inputs for each year.
Speak to a lawyer
Tell us what's going on. We review every enquiry personally and reply within 24 working hours.
Schedule a Consultation
Takes under a minute. We'll come back to you within 24 working hours.
Request received.
Thank you — a Candour Legal advocate will contact you within 24 working hours.
Urgent? Call us right away.
Disclaimer — Bar Council of India
As per the rules of the Bar Council of India, advocates and law firms are not permitted to solicit work or advertise. This website is intended solely to provide general information about Candour Legal and its areas of practice, and is made available to the user only at the user's own specific request. The contents of this website do not constitute, and should not be construed as, legal advice, an advertisement, a solicitation or an invitation of any kind. Candour Legal assumes no liability for any action taken in reliance on the material on this website; readers facing a legal issue should seek appropriate professional advice on their specific circumstances. Use of this website, or transmission of any enquiry through it, does not create a lawyer-client relationship between the user and Candour Legal.
BEFORE YOU GO
Get a free 15-minute case assessment
Tell us what's going on and a Candour Legal advocate will call you back — no charge, no obligation.
Schedule my free assessment Call now