


An issuer-focused guide to legal due diligence, DRHP disclosures, promoter verification, litigation searches, corporate compliance and IPO readiness for NSE Emerge and BSE SME listings.
Legal position reviewed on .
SME IPO legal due diligence is the systematic examination of a company’s legal, corporate, regulatory, contractual and litigation records before its initial public offering. It helps identify material risks, verify disclosures in the Draft Red Herring Prospectus (DRHP) or draft prospectus, and assess compliance with the Companies Act, 2013, SEBI’s ICDR Regulations, 2018, and applicable stock-exchange requirements.
For companies preparing to list on NSE Emerge or BSE SME, legal due diligence is not merely a documentation exercise. It is an essential part of preparing a privately managed business for public-market accountability.
This guide explains the principal areas of review, common legal deficiencies, practical compliance measures and the role of IPO legal advisors in India.
1. Why legal due diligence matters in an SME IPO
An SME IPO introduces obligations that are materially different from those faced by an unlisted private company. Corporate information that may previously have been accessible only to shareholders, lenders or regulators becomes relevant to prospective public investors.
Legal due diligence therefore serves three connected purposes:
- Regulatory readiness: Identifying whether the issuer satisfies applicable legal and listing requirements.
- Disclosure integrity: Ensuring that material information in the offer document is accurate, complete and appropriately supported.
- Risk remediation: Resolving or adequately disclosing legal deficiencies before the issue proceeds.
Chapter IX of the SEBI ICDR Regulations governs initial public offerings by small and medium enterprises. Unless a provision specifies otherwise, the issuer must meet Chapter IX conditions both when it files its draft with the SME exchange and when it files the offer document with the Registrar of Companies. ICDR regulation 227.
Legal diligence supports the statutory and regulatory responsibilities of the issuer and transaction participants. It does not eliminate those responsibilities or guarantee approval or listing.
2. The legal framework governing SME IPO due diligence
The principal legal framework includes:
| Legislation or regulatory framework | Relevance to due diligence |
|---|---|
| Companies Act, 2013 | Corporate records, share capital, governance, prospectus obligations and statutory compliance |
| SEBI ICDR Regulations, 2018 | IPO eligibility, offer-document disclosures, issue structure and SME-specific requirements |
| Securities Contracts (Regulation) Act, 1956 and Rules, 1957 | Securities listing and related regulatory requirements |
| NSE Emerge / BSE SME rules | Exchange-specific eligibility, filing and listing requirements |
| SEBI LODR Regulations, 2015 | Applicable continuing obligations after listing |
| SEBI PIT Regulations, 2015 | Insider-trading controls and handling of unpublished price-sensitive information |
| Sector-specific legislation | Licences, environmental approvals, employment, tax, property and operational compliance |
SEBI’s published consolidated ICDR Regulations were last amended on 21 March 2026, while the NSE Emerge eligibility page was updated on 12 November 2026. These are important primary references for an IPO readiness review. SEBI ICDR consolidated text NSE Emerge criteria.
An issuer must also consider subsequent applicable circulars and amendments as of its filing date. SEBI’s 14 October 2026 consultation on SME public issues proposes changes. Apply the rules in force when assessing eligibility and preparing the filing. SEBI consultation paper.
3. SME IPO eligibility: The first legal checkpoint
Before undertaking extensive due diligence, the issuer and its advisors should assess eligibility under the applicable SEBI and exchange frameworks. Under regulation 229, the Chapter IX capital threshold is measured by post-issue paid-up capital. The regulation covers issuers up to ₹10 crore and also permits those above ₹10 crore and up to ₹25 crore to use this route. ICDR regulation 229(1)–(3).
For NSE Emerge, the published criteria include:
| Requirement | NSE Emerge criteria |
|---|---|
| Incorporation | Company incorporated in India under the applicable Companies Act |
| Post-issue paid-up face-value capital | Not more than ₹25 crore |
| Track record | Generally at least three years through an eligible issuer, promoter or predecessor business route |
| Operating profit | At least ₹1 crore in operating profit (earnings before interest, depreciation and tax) from operations in each of at least two of the three previous financial years |
| Net worth | Positive |
| Free cash flow to equity | Positive in at least two of the preceding three financial years |
| Offer for sale | Aggregate offer for sale capped at 20% of total issue size. Each seller may offer up to 50% of its own pre-issue holding on a fully diluted basis. |
| Use of proceeds | Issue proceeds cannot be used, directly or indirectly, to repay loans taken from a promoter, the promoter group or any related party. |
The operating-profit floor, offer-for-sale limits and promoter-related loan restriction also apply under Chapter IX. NSE’s positive free-cash-flow-to-equity test is exchange-specific. For BSE SME, the published criteria require net worth of at least ₹1 crore in each of the two preceding full financial years and net tangible assets of ₹3 crore in the last preceding full financial year. BSE sets out additional conditions for track record, including specific treatment of predecessor businesses. ICDR regulation 229(6) Regulation 230(1)(f)–(h) BSE SME criteria.
The NSE circular dated 20 April 2026 also revised the calculation of free cash flow to equity by including proceeds from issuance of capital in the specified methodology. Use the preceding three years’ restated financial statements and exclude stub periods and projections. NSE circular and calculation examples.
Legal implications
Eligibility must be examined using verified financial records, shareholding information, corporate history and applicable exchange rules.
Where a company has undergone conversion, amalgamation, restructuring or substantial changes in its business, the legal review should examine how those events affect its track record and eligibility. Check the one-full-financial-year requirement after conversion from a proprietorship, partnership or LLP. A complete change of promoter, or acquisition of more than 50% by new promoters, also triggers a one-year waiting period from the final change before filing the draft. ICDR regulation 229(4)–(5).
A preliminary eligibility assessment should be completed before significant expenditure is committed to the IPO process.
4. Complete SME IPO legal due diligence checklist
The following checklist identifies the principal workstreams ordinarily considered in an issuer-side legal review. The precise scope depends on the issuer’s business, the transaction structure and the agreed responsibilities of its advisors.
A. Corporate records and statutory compliance
The legal team should review the issuer’s legal existence, corporate history and statutory records.
Key documents include the certificate of incorporation, memorandum and articles of association, statutory registers, annual returns, board and shareholder resolutions, and relevant Registrar of Companies filings.
Particular attention should be paid to:
- Historical changes in authorised, issued, subscribed and paid-up share capital.
- Past allotments, transfers, buybacks, bonus issues and rights issues.
- Compliance with applicable private-placement requirements.
- Outstanding charges, debentures and convertible instruments.
- Corporate approvals for restructuring and the proposed IPO.
- Inconsistencies between statutory registers, financial statements and MCA records.
An irregular allotment or missing corporate approval may require investigation, remediation or disclosure. Reconcile allotments with returns of allotment, share certificates or depository records and the register of members. Identify board or shareholder approvals that were required at the time. Companies Act, including sections 39, 42, 56, 62 and 88.
B. Promoters, directors and key managerial personnel
Promoter and management due diligence examines the legal history and relevant disclosures concerning individuals who control or manage the issuer.
The review should cover identity and directorship records, shareholding, disqualification status, relevant regulatory orders, material litigation, related business interests and applicable declarations.
Check the issuer, its promoters, promoter group, directors and selling shareholders against SEBI capital-market debarments. Regulation 228 also addresses connections to other debarred companies, wilful defaulters and fraudulent borrowers, fugitive economic offenders, and outstanding convertibles or equity rights, subject to its specific exceptions. ICDR regulation 228.
A promoter’s involvement in another company facing regulatory proceedings does not automatically establish disqualification in every case. The applicable legal provision, factual relationship and regulatory order must be assessed.
C. Litigation searches and legal proceedings
Litigation due diligence is one of the most important components of an SME IPO.
The review should examine proceedings involving the issuer and other persons or entities within the applicable disclosure scope, including promoters, directors, subsidiaries and group companies where required.
Relevant matters may include civil litigation, commercial disputes, criminal proceedings, tax disputes, arbitration, insolvency proceedings, regulatory actions and material notices.
Litigation searches should be conducted using appropriate identifiers and official records, including court and tribunal databases and available regulatory records. Searches should be supplemented by management declarations, internal registers, legal notices and confirmations from relevant counsel.
The diligence team should record:
| Field | Information to verify |
|---|---|
| Case identification | Court, tribunal, case number and parties |
| Nature of proceedings | Civil, criminal, regulatory, tax or other |
| Financial exposure | Claimed amount, provision or contingent exposure where applicable |
| Procedural status | Pending, disposed of, appealed or stayed |
| Materiality | Relevance under applicable disclosure standards |
| Documentary support | Pleadings, orders, notices and counsel confirmations |
A search showing no results is not conclusive proof that no proceedings exist. Name variations, incomplete indexing and unreported proceedings can limit search coverage.
NSE’s eligibility criteria specifically address litigation records, regulatory action, financial defaults and certain director-related criminal proceedings. NSE Emerge disclosure requirements.
D. Material contracts and financing arrangements
The review should identify contracts that are material to the issuer’s operations, finances or legal obligations.
These may include customer and supplier agreements, distribution arrangements, technology licences, leases, financing agreements, guarantees, security documents and shareholder arrangements.
Particular attention should be paid to change-of-control provisions, termination rights, exclusivity restrictions, consent requirements, financial covenants and obligations triggered by the proposed IPO.
For example, a loan agreement may require lender consent before changes in shareholding or corporate structure. A significant commercial agreement may contain termination rights that affect business continuity.
E. Property, land and intellectual property
The legal team should verify ownership, possession or lawful use of material business assets.
For land and buildings, this may involve reviewing title deeds, lease agreements, encumbrance records, permitted land use, material approvals and pending property disputes.
For intellectual property, the review should examine trademarks, patents, copyrights, software licences, domain names and material assignment or licensing arrangements.
The diligence exercise should distinguish between assets legally owned by the company and assets used under licences, leases or informal arrangements.
F. Employment and labour-law compliance
Employment due diligence should examine compliance with applicable labour and employment laws, particularly where the issuer has substantial manufacturing operations or a significant workforce.
Relevant areas include employment contracts, statutory wage and social-security compliance, gratuity obligations, contract labour, workplace safety, employee disputes and prevention of sexual harassment obligations.
The review should be tailored to the issuer’s sector, workforce structure and locations.
Material unresolved employment liabilities or regulatory proceedings may require disclosure and corrective action.
G. Licences, permits and sector-specific approvals
An issuer should maintain a verified register of material licences and approvals necessary for its operations.
Depending on the industry, these may include factory licences, environmental consents, fire approvals, food or pharmaceutical licences, import-export authorisations and other sector-specific permissions.
The review should determine whether each approval is valid, renewable, transferable where necessary and held by the correct legal entity.
Operating through an expired or incorrectly held material licence can create both compliance and disclosure risks.
H. Related-party transactions
Related-party transactions require particular attention because they may affect governance, financial reporting and the use of IPO proceeds.
The review should identify related parties and examine material transactions, loans, guarantees, advances, asset transfers and other arrangements.
Legal advisors should verify relevant corporate approvals and applicable disclosure requirements, while coordinating with auditors on accounting classification and financial reporting.
Transactions involving promoters or related entities should also be reviewed against applicable restrictions on the objects of the issue.
I. Objects of the issue and utilisation of proceeds
The objects of the issue should be supported by reliable documents and a coherent business rationale.
For proposed capital expenditure, supporting evidence may include quotations, project estimates, property documents and implementation plans.
For working capital, the financial assumptions and supporting certifications should be reviewed with the relevant financial advisors.
Legal counsel should examine whether the proposed utilisation is permitted and whether material legal or contractual conditions affect implementation.
Regulation 230 prohibits direct or indirect use of issue proceeds to repay a loan from a promoter, the promoter group or a related party. For general corporate purposes, the cap is the lower of ₹10 crore and 15% of the amount raised by the issuer. Separate limits apply to unidentified acquisitions or investments. ICDR regulation 230(1)–(3) SME IPO use-of-proceeds guide.
J. Offer-document verification
The final diligence workstream is the systematic verification of material statements in the draft prospectus, DRHP, RHP or prospectus, as applicable.
A verification process should connect factual statements with supporting documents, confirmations or other reliable evidence.
It should also identify unresolved questions, inconsistent information and disclosures that require updating before filing.
The legal team should work with the issuer, merchant banker, auditors, company secretary and other transaction participants to reconcile material information.
NSE’s published process states that draft prospectuses must comply with the applicable ICDR Regulations and other relevant laws. It also cautions that NSE’s examination of a draft prospectus for listing purposes should not be construed as approval under every applicable law. NSE Emerge filing process.
5. Interactive SME IPO legal readiness checklist
Tick each item once the supporting evidence has been reviewed. You can copy the checklist with its current review status. This internal readiness assessment is not a substitute for transaction-specific legal due diligence.
Pre-IPO due diligence tracker
Illustrative internal readiness assessment
0% · 0 of 17 items reviewed
6. Common legal deficiencies identified during IPO preparation
Several categories of deficiencies can delay an IPO or require additional work before an offer document is finalised.
| Deficiency | Potential implication | Recommended response |
|---|---|---|
| Incomplete statutory records | Inconsistent corporate disclosures | Reconcile registers and MCA filings |
| Unreported litigation | Incomplete risk or litigation disclosures | Conduct searches and obtain confirmations |
| Missing property documentation | Uncertainty over material asset rights | Verify title, leases and encumbrances |
| Undocumented related-party transactions | Governance and disclosure concerns | Review records, approvals and applicable law |
| Expired material licences | Operational or regulatory exposure | Assess renewal, remediation and disclosure |
| Unresolved promoter shareholding issues | Capital structure and eligibility concerns | Reconcile holdings and legal instruments |
| Unsupported use-of-proceeds estimates | Inadequate issue-object substantiation | Obtain appropriate supporting evidence |
Not every deficiency prevents an IPO. The appropriate treatment depends on applicable law, materiality, whether the matter can be remedied and the disclosure requirements.
7. What is the role of an IPO legal advisor?
An IPO legal advisor assists the issuer or another transaction participant, depending on the engagement, with the legal aspects of preparing and executing a public offering.
The scope may include corporate due diligence, litigation searches, legal opinions, transaction documentation, review of material contracts, offer-document drafting and verification, and advice on relevant regulatory obligations.
A distinction should be maintained between the responsibilities of legal counsel and those of the lead merchant banker.
Under the applicable capital markets framework, the lead merchant banker has its own due diligence and regulatory responsibilities. Engaging external legal counsel does not transfer those responsibilities to the law firm. Similarly, legal counsel does not replace the issuer’s auditors or other specialist advisors. The lead manager must verify the adequacy and accuracy of disclosures. At draft filing it submits the Form A due-diligence certificate with its site-visit report, Form G confirmations and draft abridged prospectus to the proposed SME exchange. ICDR regulations 245(3) and 246(3).
When should a company appoint IPO legal counsel?
Ideally, legal diligence should begin before the first substantive draft of the offer document.
Early appointment allows sufficient time to investigate historical corporate issues, obtain missing documents, examine litigation, resolve material deficiencies and coordinate with the merchant banker.
The appropriate timeline depends on the complexity of the business, the quality of existing records and the transaction timetable.
8. Legal due diligence does not end with the DRHP
Legal due diligence is often described as a pre-filing exercise, but material developments may arise between the draft offer document, final offer document, issue opening and listing.
These may include new litigation, regulatory proceedings, material contracts, changes in shareholding, corporate approvals or other developments requiring reassessment.
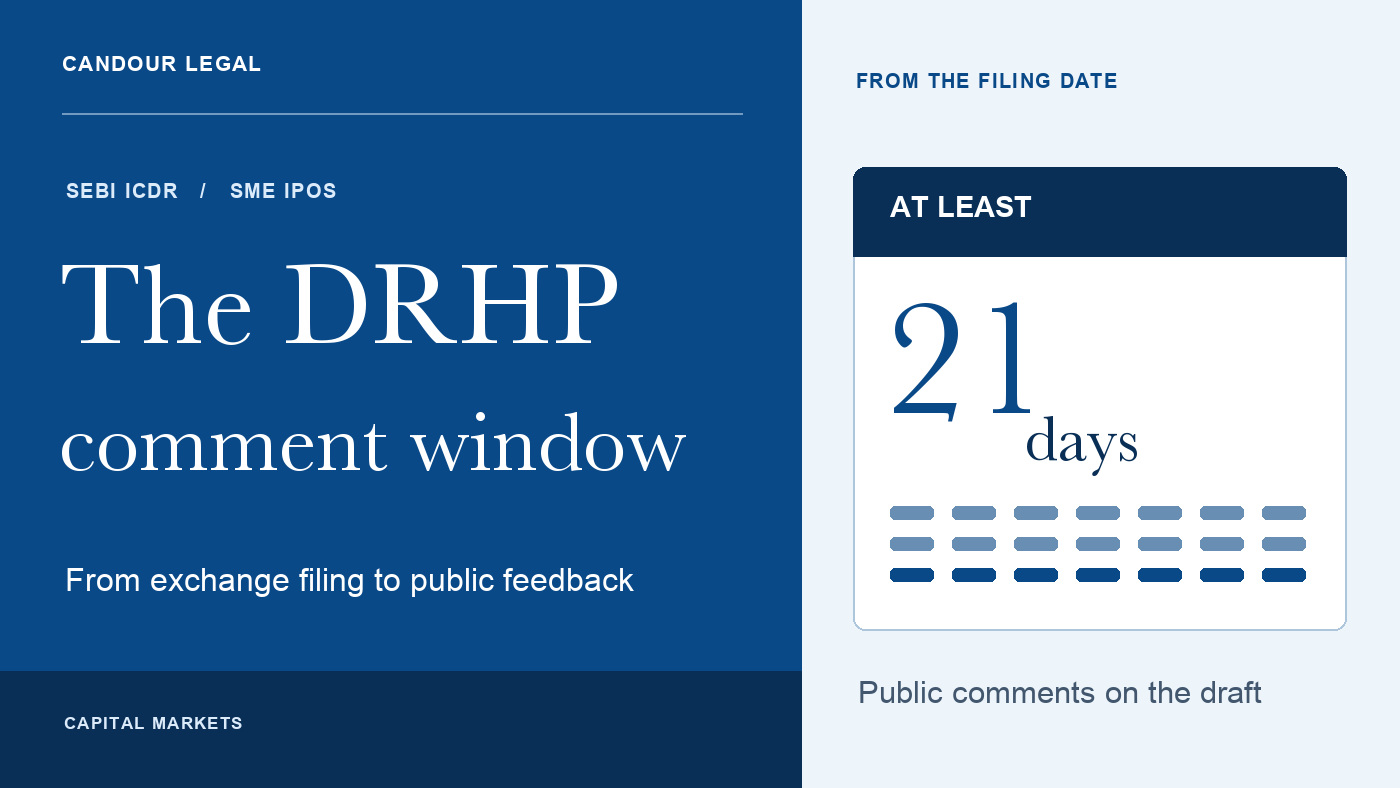
A practical transaction process should therefore include mechanisms for updating diligence findings and verifying disclosures at relevant milestones. Regulation 247 provides at least 21 days from filing for public comments. Within two working days of filing, the issuer must announce the filing in the prescribed newspapers. The lead manager must report comments and consequential changes to the exchange after the period closes. ICDR regulation 247 DRHP public-comments guide.
Following listing, the company must also establish processes for applicable continuing disclosure, governance and insider-trading obligations.
9. Candour Legal Insight™: The importance of disclosure integrity
For SME companies, legal due diligence is especially important because many businesses approach public markets after operating for years under promoter-led management structures.
Such businesses may have strong commercial performance while still requiring improvements in corporate documentation, contractual governance, compliance systems and record maintenance.
A recurring challenge in IPO preparation is the assumption that legal diligence can be completed through a checklist of documents alone.
In practice, effective due diligence requires identifying relationships between documents, testing the consistency of representations and determining whether the legal position supports the disclosures proposed in the offer document.
A litigation search, for example, should not simply produce a list of proceedings. It should identify the relevant parties, legal issues, status, material exposure and disclosure implications.
Similarly, corporate diligence should not merely confirm that statutory registers exist. It should reconcile the legal history of share capital with underlying approvals, filings and financial records.
The quality of legal due diligence is measured not only by the number of documents reviewed, but by the reliability of the conclusions and disclosures that follow.
Candour Legal’s IPO advisory practice
Candour Legal is an Ahmedabad-based Indian law firm advising on corporate law, securities-law matters, IPO documentation and legal compliance.
Its capital markets work includes legal due diligence and IPO-related documentation, including litigation and corporate disclosure reviews, subject to the scope of individual engagements.
For companies evaluating an SME IPO, early legal preparation can help identify issues requiring attention before formal filing.
10. Frequently asked questions about SME IPO legal due diligence
What is legal due diligence in an SME IPO?
It is the examination of an issuer’s legal and regulatory position, including corporate records, litigation, contracts, licences, promoters, shareholding and relevant disclosures before a public offering.
Is legal due diligence mandatory for an SME IPO?
An SME IPO is subject to mandatory eligibility, disclosure and other regulatory requirements. The lead merchant banker’s due diligence obligations are distinct from the question of whether an issuer must appoint a separate external law firm for every workstream. The precise requirements and responsibilities depend on the applicable framework and engagement structure.
What documents are required for IPO legal due diligence?
Common documents include incorporation records, statutory registers, shareholding records, board resolutions, financial and financing documents, material contracts, property documents, licences, litigation records and promoter declarations.
How long does SME IPO legal due diligence take?
There is no universal completion period. The duration depends on the company’s size, group structure, documentation, litigation exposure, number of locations and responsiveness to diligence requests.
Can a company with pending litigation launch an SME IPO?
Pending litigation does not automatically prohibit an IPO. However, relevant proceedings must be assessed against applicable eligibility restrictions and disclosure requirements. Their materiality and legal consequences may affect the transaction.
Who conducts litigation searches for an SME IPO?
Litigation searches may be conducted by legal counsel or other authorised diligence teams, depending on the transaction. Searches should use appropriate official records and be supported by confirmations and relevant case documents.
What is the difference between an IPO legal advisor and a merchant banker?
The merchant banker performs regulated issue-management functions and carries specified responsibilities under securities regulations. Legal counsel advises on legal matters within its mandate, including due diligence, documentation and disclosures.
Does the SME IPO legal checklist differ for NSE Emerge and BSE SME?
The principal statutory and SEBI framework is common, but exchange-specific eligibility, filing and procedural requirements may differ. Each proposed listing must be assessed against the relevant exchange’s current requirements.
11. Conclusion
SME IPO legal due diligence is a foundational part of preparing a company for public-market participation.
A comprehensive review helps identify legal risks, verify corporate records, examine litigation and material contracts, assess regulatory compliance and support accurate disclosures in the offer document.
For promoters and management teams, the most effective approach is to begin the legal review early and maintain it throughout the IPO process.
Companies considering an SME listing should evaluate their legal readiness alongside financial eligibility, commercial objectives and the requirements of the relevant stock exchange.
Further reading from Candour Legal:
- IPO legal advisory services
- Legal framework for SME IPOs in India
- NSE Emerge eligibility and financial readiness
- SME IPO promoter contribution and lock-in
- SME IPO offer-for-sale limits
- SME IPO use of proceeds
- Reading a draft prospectus and raising a disclosure issue
Primary legal and regulatory references
- SEBI ICDR Regulations, consolidated through 21 March 2026
- NSE Emerge eligibility criteria, updated 12 November 2026
- NSE circular dated 20 April 2026 — revised FCFE methodology
- NSE circular dated 23 December 2024 — additional eligibility criteria
- BSE SME listing eligibility criteria
- NSE Emerge filing requirements and checklists
- Companies Act, 2013 — official India Code text
- SEBI consultation paper on SME public issues, 14 October 2026
- SEBI consolidated regulations index
Disclaimer: This article provides general legal information and does not constitute legal advice, investment advice or a solicitation. Regulatory requirements should be assessed against the law and circulars applicable to the specific transaction.
Speak to a senior advocate about your matter.
Tell us what's going on. We review every enquiry personally and reply within 24 working hours.
Schedule a Consultation
Takes under a minute. We'll come back to you within 24 working hours.
Request received.
Thank you — a Candour Legal advocate will contact you within 24 working hours.
Urgent? Call us right away.
Disclaimer — Bar Council of India
As per the rules of the Bar Council of India, advocates and law firms are not permitted to solicit work or advertise. This website is intended solely to provide general information about Candour Legal and its areas of practice, and is made available to the user only at the user's own specific request. The contents of this website do not constitute, and should not be construed as, legal advice, an advertisement, a solicitation or an invitation of any kind. Candour Legal assumes no liability for any action taken in reliance on the material on this website; readers facing a legal issue should seek appropriate professional advice on their specific circumstances. Use of this website, or transmission of any enquiry through it, does not create a lawyer-client relationship between the user and Candour Legal.
BEFORE YOU GO
Get a free 15-minute case assessment
Tell us what's going on and a Candour Legal advocate will call you back — no charge, no obligation.
Schedule my free assessment Call now